

Menu
Transparency, accountability, and risk management are central to the governance dimension of ESG. The G20/OECD Principles of Corporate Governance 2023 emphasize clearly defined responsibilities, disclosure of material information, and effective oversight and risk management. Although these principles address corporate governance more broadly, the same concerns extend to day-to-day operations, particularly in processes involving approvals, contracts, and invoices. Clearly defined approval procedures, assigned responsibilities, invoice verification, and systematic recordkeeping help businesses strengthen internal controls and translate governance policies into practice.
Building Accountability Through Approval Workflows
Delegating authority is about more than deciding who can approve a request. It also means ensuring that decisions remain within established authority, follow the required procedures, and can be reviewed afterward. Consider a typical procurement process: a department manager confirms the business need, the finance team checks budget availability, and an authorized manager grants final approval. FPT.SPro allows organizations to configure workflows around their organizational structures and internal approval policies, automatically routing requests to the appropriate personnel at each stage. These predefined workflows help reduce misrouted requests, missed approval steps, and reliance on manual coordination between departments.
Clear approval rules are only part of the picture. Organizations also need visibility into what happens as a request moves through the process. With FPT.SPro, authorized users can see where a request stands, who is responsible for the next step, which approvals have been completed, and whether any delays have occurred. Keeping records and processing histories in one place also makes it easier to review decisions and establish responsibility during internal checks.
From Contracts to Invoices: Creating a Clear Audit Trail
At the contract stage, FPT.eContract supports defined signing sequences, signer authentication, and records of contract status and signing history. When integrated with relevant business systems, these capabilities allow organizations to follow a transaction from approval through contract execution, rather than relying solely on the final signed document to understand how a decision was made.
FPT.eInvoice adds another layer of checks at the invoicing stage. Where the relevant incoming-invoice processing features and data integrations are in place, the solution can check invoice details, verify whether an invoice is recorded in the tax authority’s system, and compare invoice information with purchase orders and goods-receipt records, a check known as three-way matching. If an invoice amount differs from the corresponding purchasing information, the system can help flag the discrepancy for further review before processing continues. Such checks give accounting and finance teams a more systematic way to identify transactions that require attention, reducing their reliance on manual verification alone.
Strengthening Access Control and Information Security
Greater visibility, however, must be balanced with information security. The person who submits a request, the manager who approves it, and the team responsible for reviewing it may all need different levels of access. FPT.SPro can route approval tasks according to an organization’s internal structure and designated responsibilities. For document management, FPT.SPro offers secure-sharing features that allow organizations to set access permissions, sharing expiration dates, and authentication requirements.
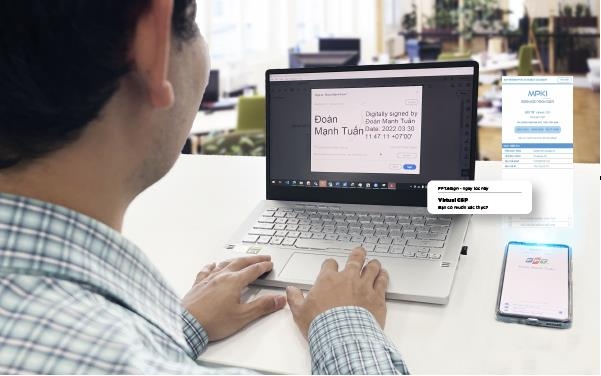
FPT.eContract also supports signer authentication, maintains signing records, and incorporates multiple layers of security to protect contract information. FPT.eInvoice supports authentication of transmitted invoice data, helping organizations maintain reliable information exchanges between systems. Together, these capabilities can help organizations define responsibilities, manage access to business information, and preserve records for internal review.
Across approval workflows, contract management, and electronic invoicing, the FPT IS digital ecosystem can therefore help reinforce governance controls at the operational level. By making responsibilities clearer and transaction histories more accessible, these tools provide information that organizations can use to review decisions, examine discrepancies, and identify potential risks.
Why Invoice Data Matters for ESG Governance
The scale of digital transactions makes these capabilities increasingly relevant. According to Vietnam’s Ministry of Finance, the country’s electronic invoicing system received nearly 8.5 billion invoices in 2025 alone. The figure illustrates the scale of electronic invoicing in Vietnam. For individual businesses, however, the governance challenge extends beyond maintaining complete records. Organizations must also be able to detect discrepancies promptly and establish the basis for individual decisions.
The importance of effective internal controls is also reflected in international fraud research. In Occupational Fraud 2026: A Report to the Nations, the Association of Certified Fraud Examiners (ACFE) found that more than half of the occupational fraud cases examined involved either a lack of internal controls or the override of existing controls. While these findings are not a direct measure of fraud among Vietnamese businesses, they underscore a broader point: moving a process online does not, by itself, mean its risks are effectively managed.
From Digitalization to Continuous Governance Improvement
The long-term value of a paperless office, then, should not be measured simply by the number of documents or workflows moved into digital systems. Its contribution to ESG governance also depends on whether the information those systems generate can support meaningful oversight and continuous improvement. When approval records, contracts, and invoices are managed systematically, alongside appropriate access controls, exception reviews, and periodic assessments, organizations are better positioned to identify weaknesses and address them before they develop into more serious risks. Technology can make that scrutiny possible, but it cannot replace effective governance. Ultimately, stronger internal controls depend on how consistently organizations enforce their policies, assign accountability, and act on the information available to them.
Read more:
– Paperless Office: How the FPT IS Digital Ecosystem Drives the Twin Transition and Supports ESG Goals
– Paperless Office and ESG: Reducing Paper Consumption and Preventing Waste in Line with GRI 306